

Smaller Pulse Crops Should Support the 2026/27 Price Outlook
The combination of reduced acreage and lower yields than last year mean smaller pulse crops in 2026. The drop in production should be no surprise, especially since it would be difficult to repeat the very high yields of 2025. And together with positive signals for export demand, the smaller crops will support prices in 2026/27. The only fly in the ointment will be the large old-crop supplies left over at the end of 2025/26.
The StatsCan 2026 yield estimate for peas came in at 40.6 bu/acre, compared to 42.3 bu/acre last year. That’s also close to yields reported by Alberta Ag and Sask Ag in recent crop reports. Not all the crop has been harvested yet, but the yield is likely close to reality. This puts the 2026 pea crop at 3.26 mln tonnes, 675,000 tonnes less than last year. Based on the acreage breakdown, yellow pea production would drop a bit more than greens.
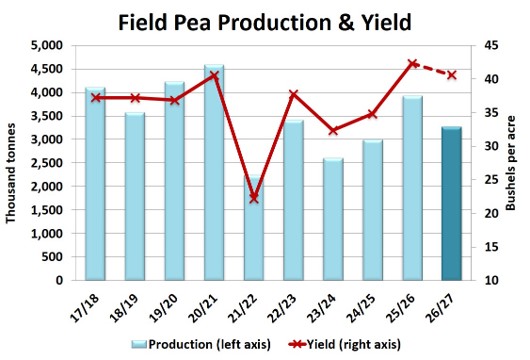
The problem in the pea market is that the carryover from 2025/26 was record large, which essentially offsets the drop in production and leaves supplies almost the same as 2025/26. The good news is that demand for yellow peas is expected to be very strong, with both India and China both in the market while Russia is facing shipping difficulties. That will have a bigger price impact on yellows than greens, but bids for both are already starting to respond.
The lentil yield estimate from StatsCan dropped sharply to 1,415 lb/acre from last year’s high of 1,722 lb/acre, although that’s still above average. When the 18% yield decline is combined with 11% fewer acres, the 2026 lentil crop would be 900,000 tonnes (27%) smaller than last year. Just like peas, the old-crop carryover for lentils is record large and 2026/27 supplies are only 150,000 tonnes less than the year before. And small green lentil supplies are particularly heavy.
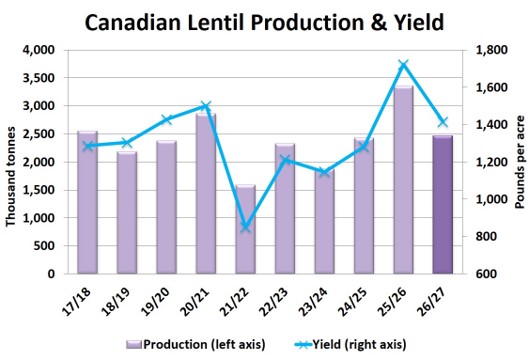
The lentil situation is also similar to peas in that demand is expected to be stronger in 2026/27. A lot of that outlook is based on expectations that India will be a larger buyer of both red and green lentils, but other destinations should also take sizable volumes. The main check on Canadian exports, particularly reds, is the record crop in Australia.
Seeded area of chickpeas was only slightly lower in 2026 but the StatsCan yield of 1,691 lb/acre is 14% lower than last year at 1,970 lb/acre. The result is a 2026/27 chickpea crop of 400,000 tonnes, 80,000 tonnes less than last year. But following the common theme, old-crop carryover is very large and would more than wipe out the impact of the smaller crop. Of course, for chickpeas, all this depends on getting chickpeas off the field, a serious challenge. The chickpea outlook is also similar to peas and lentils in that export demand should be even larger than the record program of 2025/26.
Just like other pulses, dry bean acreage declined in 2026/27, although yields could be slightly higher. The StatsCan production estimate of 355,000 tonnes is 19% smaller than last year, but more importantly, the US crop is also expected to drop sharply, with black and pinto bean production falling the most. The dry bean market is already rallying.
Pulse Market Insight provides market commentary from Chuck Penner of LeftField Commodity Research to help with pulse marketing decisions.