Contact

Pulse Market Insight #295

Are US Acreage Changes a Signal for Canada?

A few weeks ago, StatsCan released its seeding intentions estimates for 2026, but these were the results from a very early farmer survey. This raised lots of questions about whether farmers have changed some planting decisions since then. This past week, the USDA issued its own set of 2026 acreage forecasts, but these survey results were more current by a couple of months.

Farmers on both sides of the border generally see the same kind of price signals and cropping practices aren’t all that different. As a result, we wonder whether the more recent USDA estimates could provide a few fresh clues about acreage changes in western Canada.

In its estimates, the USDA is forecasting seeded area of peas at 1.17 mln acres, almost identical to 2025, and this would be the second highest total ever. This is a bit surprising, given that US pea exports have lagged in 2025/26 and prices there haven’t benefited from Chinese buying, like Canadian peas have.
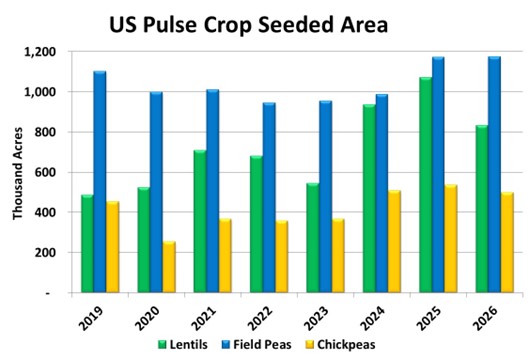
Earlier, StatsCan forecast a 12% decline in Canadian pea acreage but again, this was based on a farmer survey conducted before China dropped its import tariffs. It’s quite possible that the Canadian acreage number will be revised higher and if it matches the 2025 total, the 2026/27 supply outlook could be more comfortable than expected earlier.

The USDA reported a much larger change for 2026 lentil acres, with a 22% drop in seeded area at 832,000 acres. That shouldn’t be all that surprising as 2025 acreage was a near record and a return to more typical levels could be expected. More importantly, a large portion of US lentils are green varieties (mainly medium greens), and those prices have seen large price declines, discouraging more acres.

In western Canada, StatsCan estimated a more moderate 5.5% decline in lentil acreage. But looking beneath the surface, seeded area of green lentils will almost certainly drop more sharply, which could mirror the US declines. At the same time, red lentil acreage in western Canada will likely see an increase.

Seeded area of chickpeas in the US is forecast to drop by 7% in 2026. That’s the opposite direction from StatsCan’s estimate of a 6% increase. If 2026 chickpea acreage remains fairly steady on both sides of the border, that wouldn’t be too surprising. That said, these changes are relatively minor and we don’t want to read too much into them, especially since both the USDA and StatsCan have made sizable revisions to their chickpea estimates in recent years.

The USDA pulse estimate that could be the strongest clue about Canadian acreage is for dry beans, which are forecast to decline 10% from last year. StatsCan’s dry bean acreage estimates were incomplete for several provinces, and those gaps made it difficult to get a good handle on Canadian acreage. If seeded area on both sides of the border declines by 10%, lower North American supplies could make the 2026/27 market a bit more interesting.
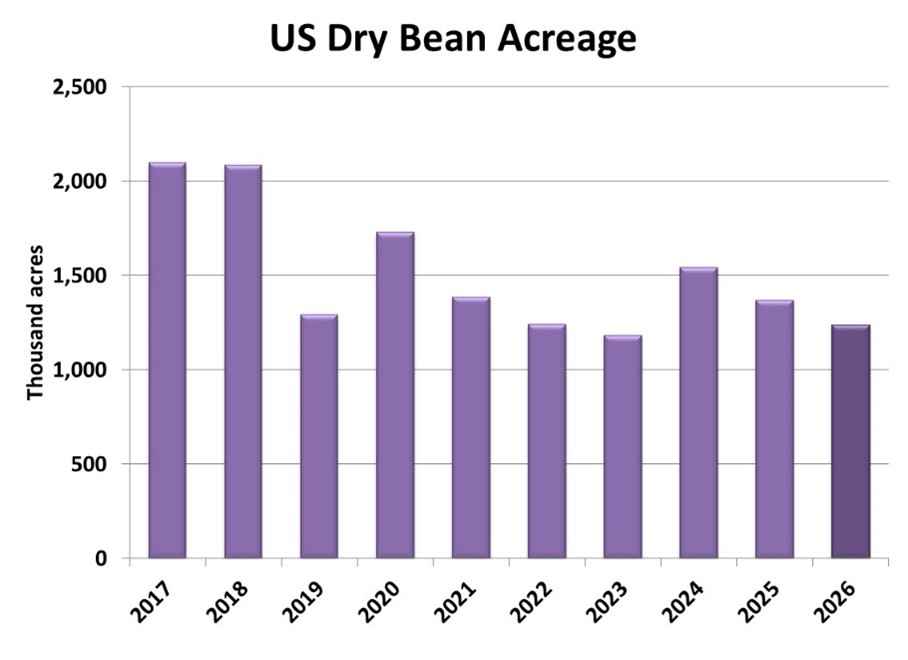
Of course, these are only acreage numbers. The main ingredient in the supply outlook is yield. At this point, we think in terms of average yields, and there’s no way to make an accurate forecast until well into the growing season.

Pulse Market Insight provides market commentary from Chuck Penner of LeftField Commodity Research to help with pulse marketing decisions.
Alberta crop & livestock producers welcome emergency authorization of strychnine

Alberta crop and livestock producer organizations are welcoming the Government of Alberta’s success in securing an emergency use registration of strychnine to help manage Richardson Ground Squirrels.

This authorization provides an important and immediate tool for producers facing increasing infestations that threaten pasture, rangeland, and cropland across the province. Left unmanaged, ground squirrels can cause significant economic damage and undermine the productivity of farms and ranches that rural communities depend on.

With no viable, scalable alternatives currently available, this authorization is critical for producers dealing with widespread infestations. Strychnine remains the only proven tool that can be effectively deployed at the scale required in severe situations.

This outcome reflects sustained advocacy from Alberta’s agricultural sector and strong leadership from the provincial government. The efforts of Minister of Agriculture and Irrigation RJ Sigurdson, alongside the engagement of Premier Danielle Smith with federal counterparts, following earlier challenges in securing approval, were key to achieving this result.

We recognize the persistence required to secure this authorization and appreciate the Government of Alberta’s commitment to supporting producers and rural communities.

While this emergency registration provides needed short-term relief, producers note it is one tool within a broader approach to pest management.

Alberta’s producer organizations remain committed to working with all levels of government to ensure producers have access to effective, science-based tools to protect their operations now and into the future.

Alberta Beef Producers, Alberta-British Columbia Seed Growers, Alberta Canola, Alberta Grains, Alberta Pulse Growers, Alberta Sugar Beet Growers, Potato Growers of Alberta


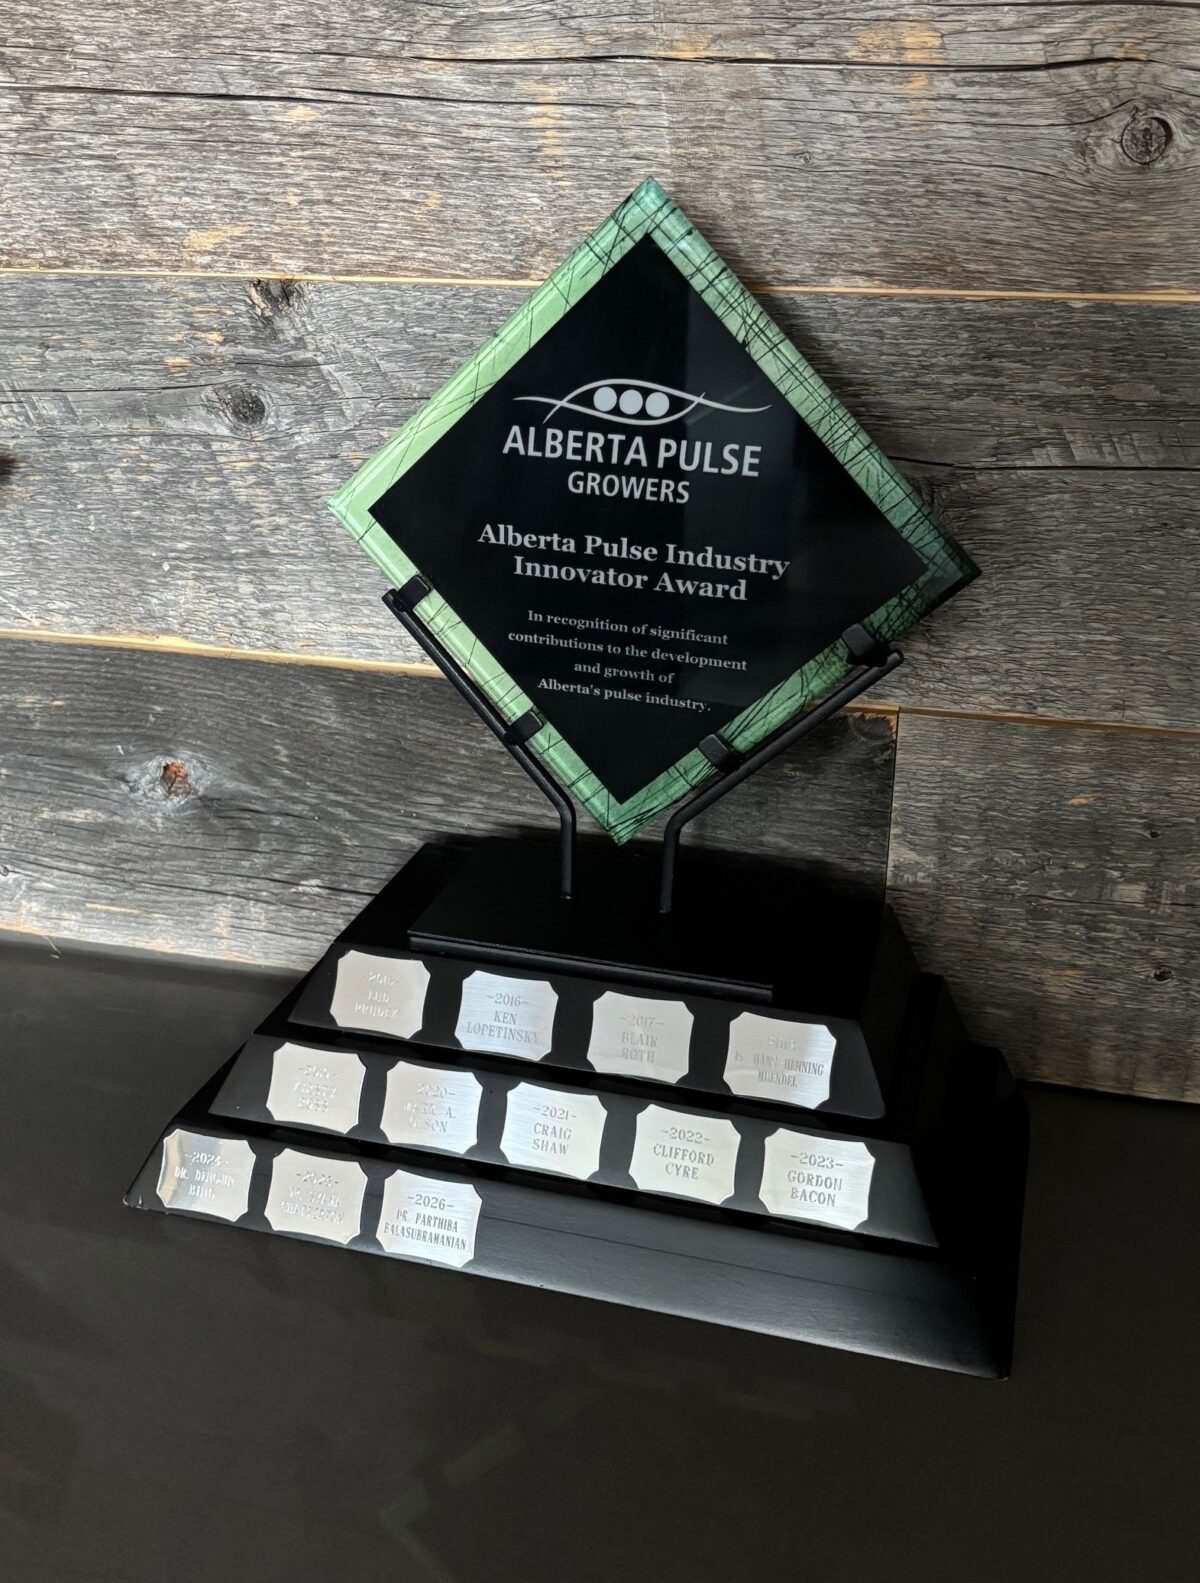
Dry Bean Breeder Dr. Parthiba Balasubramanian honoured with 12th Annual Alberta Pulse Industry Innovator Award

Alberta Pulse Growers (APG) selected Dr. Parthiba Balasubramanian, who continues to develop dry bean cultivars with useful traits for farmers, as the winner of the 12th annual Alberta Pulse Industry Innovator Award.

“Each year, APG recognizes a person or organization whose progressive thinking and tireless efforts helped build Alberta’s pulse industry into the flourishing sector that it is today,” said APG Chair Will Muller. “Parthiba has been responsible for developing dry bean cultivars with traits appreciated by growers in Southern Alberta, including myself.”

Alberta pulse farmers and distinguished guests were on hand to celebrate Balasubramanian and his achievements at an award lunch during recent APG Joint Director-Advisor meetings in Calgary.

Farmers recognize Balasubramanian’s research contributions that have demonstrated success and advanced the growth of pulses in their businesses. The strength, consistency and performance of the dry bean cultivars developed by his program regularly provided, and continue to provide, excellent returns to the farm gate.

“Parthiba’s traditional scientific breeding techniques and strong attention to traits combine high yield with early maturity, lodging resistance, and enhanced resistance to white mould and bacterial diseases,” Muller explained. “This is in addition to improved seed quality such as size, shape, colour and colour retention traits for commercial production under irrigated conditions in Alberta and Saskatchewan which are held in high regard by pulse farmers.”

Balasubramanian was nominated for the award by APG’s Zone 1, which is comprised of pulse farmers in the Southern Alberta region with the climate to grow dry beans. Fellow scientists celebrated Balasubramanian’s accomplishments in a video that was shown during the ceremony and is available on the APG YouTube channel.

I am truly humbled to receive this award,” said Balasubramanian, who is based at the Agriculture and Agri-Food Canada (AAFC) Lethbridge Research and Development Centre. “I accept this award on behalf of the team members who have been part of the dry bean breeding program in Lethbridge in the past and in the present. It is their hard work, dedication and work ethic that has made the accomplishments of the program possible. We have been very fortunate to receive funding from various organizations, and it is because of the funding that we have been able to do the things we do in the breeding program.”

The Alberta Pulse Growers Commission represents 5,400 growers of field pea, dry bean, lentil, chickpea, faba bean, lupin and soybean in Alberta. Our vision is to have pulses on every farm, on every plate.

For more information, please contact:
Rachel Peterson, Communications Manager
Phone: 780-986-9398 ext. 108
rpeterson@albertapulse.com
www.albertapulse.com

Pulse Market Insight #294

Mid-Season Checkup

It’s already well past the halfway point of the 2025/26 marketing year but some of the performance measures, particularly exports, are only available for January. This export data gives us a bit of an indication of how things performed through the first half of the year and admittedly, are backward looking. Since then too, some significant changes have occurred in pulse markets, particularly for peas. There are also a few risks remaining in the market that could impact the last few months of 2025/26. Still, it’s worth reviewing how the first half of the year could impact the remainder of 2025/26.

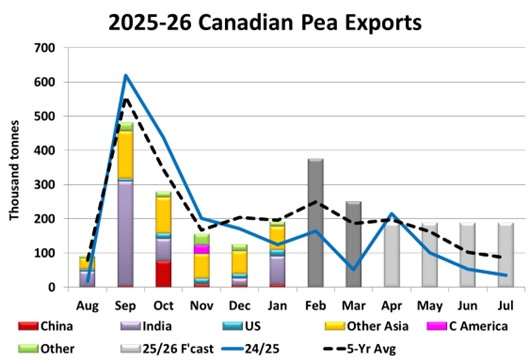
Pea exports in the first half of 2025/26 have been disappointing, but that’s not surprising. With a few small exceptions, China has been absent as a buyer, and monthly totals have mostly been below average. Canadian exports to India have been sporadic, well below year-ago levels. The main bright spot has been a near doubling in exports to other Asian countries, particularly Bangladesh.

Overall, Canadian pea exports for the first six months of 2025/26 were 1.32 mln tonnes, the slowest pace since 2021/22 and well below the 5-year average of 1.55 mln tonnes. But there is good news early in the second half of the marketing year. The CGC weekly data is more current and shows a sharp increase in February exports, which we’re forecasting at 375,000 tonnes with solid performance again in March. This reflects the return of China as a customer due to the removal of import tariffs, effective March 1. While it’s not clear how the last few months will turn out, our full-year export forecast is now 2.7 mln tonnes, which would end up the highest since 2020/21.

Canadian lentil exports dipped in January but the first-half total of 1.19 mln tonnes was still slightly ahead of average at 1.11 mln tonnes. India was the largest destination but exports to Türkiye were also very strong due to its crop failure in 2025. We expect this strong Turkish demand will continue into the second half.

While the first half export pace has been solid, the CGC data shows lentil exports (similar to peas) are also seeing an uptick in the second half. While first-half lentil exports in 2025/26 were trailing last year, CGC exports (which don’t capture container exports) have pulled ahead in the last few weeks. There are also signs in the CGC’s delivery and shipment data that these export volumes will remain strong for at least the medium-term. Our full-year export forecast for 2025/26 is 2.25 mln tonnes, more than 400,000 tonnes above the previous year.

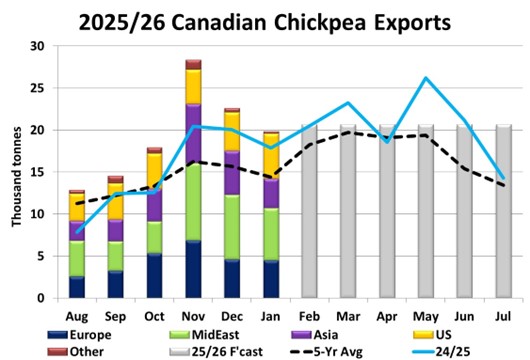
So far in 2025/26, Canadian chickpea exports are performing very well. Over the first six months, 116,200 tonnes were exported, a record pace and well above the 5-year average of 83,000 tonnes. Canadian chickpeas are competitively priced and solid exports are expected to continue, especially since volumes tend to be higher in the second half of the year. That said, Canadian supplies are still large enough to easily supply this demand.

Dry bean exports are also running at a record pace so far in 2025/26. Over the first half, 209,800 tonnes were exported compared to the 5-year average of 187,300 tonnes. As dry bean supplies are drawn down later in the year, exports could be limited, but the full-year total will be very positive.

Pulse Market Insight provides market commentary from Chuck Penner of LeftField Commodity Research to help with pulse marketing decisions.
Qualified Alberta Pulse Growers Eligible for 30.3% Tax Credit for Investing in Research

The Alberta Pulse Growers Commission (APG) has confirmed that 30.3% of eligible producers’ 2025 check-off payment is eligible for the Scientific Research & Experimental Development (SR&ED) tax credit for their investment in APG-funded research and development projects.

Producers are eligible to claim up to a maximum of 15% for non-incorporated farm operations and up to a maximum of 35% for incorporated operations of the determined 30.3%.

Producers who have paid check-off this past year and have not asked for refunds are eligible claimants for this year’s credits.

For more detailed information about the SR&ED Tax Credit, APG advises you to contact an accountant or the Canada Revenue Agency. For a history of SR&ED with Alberta Pulse Growers visit https://albertapulse.com/research-tax-credit/ . Information about APG research investments in 2024-25 is available at https://albertapulse.com/resource-library/ .

The federal SR&ED tax program is administered by the Canada Revenue Agency (CRA) and encourages businesses to invest in and perform research and development in Canada.

The SR&ED Tax Credit application forms for individual producers and Canadian controlled private corporations can be downloaded directly from the CRA website at https://www.canada.ca/en/revenue-agency/services/scientific-research-experimental-development-tax-incentive-program.html .

The Alberta Pulse Growers Commission represents 5,400 growers of field pea, dry bean, lentil, chickpea, faba bean, lupin and soybean in Alberta. Our vision is to have pulses on every farm, on every plate.

For more information, please contact:
Rachel Peterson, Communications Manager
Phone: 780-986-9398 ext. 108
rpeterson@albertapulse.com

Pulse Market Insight #293

StatsCan Pulse Acreage Numbers (Mostly) Not Surprising

The first official forecasts of 2026 seeded area were recently issued by StatsCan, with some “interesting” estimates for a few crops. For pulse crops though, most of the acreage numbers weren’t really out of line with expectations.

It’s important to note that even though StatsCan’s estimates were issued in early March, they were based on a farmer survey that occurred between mid-December and mid-January. Since that survey, there have been sizable market developments that could influence acreage decisions. That said, crop rotations are largely fixed and a portion of the acreage was already decided back in December. But there is still room for some late tweaking around the margins.

The most noteworthy event was the announcement by the Chinese government to scale back or eliminate import tariffs on canola seed, canola meal and peas, which injected more optimism into those markets. This development added some support for prices which could, in turn, shift a few more acres in that direction. Prices for other crops like barley, wheat and red lentils are moving higher seasonally, which could also make those look a bit more attractive.

For the most part though, StatsCan’s estimates a pulse crop acreage seem to be within reason. Seeded area of peas was reported at 3.08 mln acres, 12% less than last year and in line with the average trade guess. Both yellow and green pea prices are lower than a year ago, but the decline is sharper for green peas, which could discourage a few more of those acres. But as mentioned above, more certainty with respect to exports to China could bring a few more peas, particularly yellows, back into rotations.

Fewer acres of peas along with a return to an average yield would mean the 2026 crop could shrink by over a million tonnes. This should help ease the heavy supply situation to some degree but wouldn’t make things “tight”. The old-crop carryover from 2025/26 is expected to be historically large and offset much of a reduction in the 2026 crop.

StatsCan also showed a decline in 2026 lentil acreage, although not to the same extent as peas. Seeded area was reported at 4.14 mln acres, 5.5% lower than last year but above the average trade guess of 3.9 mln acres. This reduction would be fairly modest and leave lentil acreage in line with the 5-year average. While StatsCan doesn’t provide a breakdown by type in this report, we would expect a shift to red lentils, back to a more typical two-thirds share of acreage. This would mean a larger cut in green lentil acres, which the market definitely needs.

Just like peas, fewer lentil acres and a drop back to the average yield would mean a large decline in the size of the 2026 crop, a step in the right direction for a heavily-supplied market. That said, most of that production loss would be offset by the large old-crop carryover from 2025/26, with an emphasis on green lentil supplies.

Chickpeas are the exception in StatsCan’s lower estimates of pulse acreage. Seeded area is forecast at 575,000 acres, 6% more than last year. Even with more acres, a drop back to the average yield would mean a noticeably smaller crop in 2026. But the recurring theme of heavy supplies will also limit the impact of a smaller chickpea crop, with the very large old-crop carryover from 2025/26 resulting in even larger supplies next year. Export demand has been strong for chickpeas, but that may not be enough to keep supplies from feeling heavy again in 2026/27.

StatsCan’s estimate of dry bean acres was a bit puzzling, showing a 31% drop at 295,000 acres. That would be the lowest total since 2015. While prices for pinto and black beans are currently low, we’re skeptical that seeded area will decline that much, partly because StatsCan’s coverage of dry beans has been “patchy” in the past. Seeded area will likely be lower, but not by that much.

Pulse Market Insight provides market commentary from Chuck Penner of LeftField Commodity Research to help with pulse marketing decisions.

Pulse Market Insight #292

Drawing Down Pulse Stocks Will Take Time

It’s no secret that Canadian pulse crops were big in 2025. While pulse yields didn’t set new records like a few other crops, the pea yield of 42.3 bu/acre was 7½ bushels more than the year before and 26% above the 5-year average. The 2025 lentil yield of 1,721 lb/acre was up 440 pounds from the previous year and 45% above average while the chickpea yield was 1,970 lb/acre, 650 pounds more than 2024 and a whopping 56% above the average.

For all three pulse crops, seeded area was higher in 2025 than 2024, compounding the big crop “problem”. While not everyone got the high yields, the big inventories in farmers’ bins are evidence of the heavy supply situation facing pulse markets in 2025/26. Total supplies of pulses (not including dry beans) in 2025/26 are a new record, just over 9.0 mln tonnes. That’s 2.6 mln tonnes (40%) more than a year ago.

It wasn’t just the big 2025 crops that caused the buildup in supplies; stocks at the end of 2024/25 were already feeling “comfortable” for all three pulse crops. When those stocks were carried over into 2025/26 and added to last year’s big production, supplies ballooned.

The feeling of “heaviness” in the market varies between pulses and even within pulse types. For example, production of green and maple peas expanded more than yellows in 2025 and those two classes are looking a bit more burdensome than yellows. The green lentil crop, especially small greens, grew a lot more than reds, creating more of a “problem” with green lentils.

On the plus side, pulse exports in 2025/26 have been showing some positive signs. Pea exports are starting to pick up again now that the Chinese government has announced a drop in tariffs. Movement of lentils has been positive all year, with more signs of fresh demand in the last few weeks. And chickpea exports have picked up considerably this year, with volumes in November the highest in years.

Of course, stronger export demand is stimulated by low prices, which is part of normal market behaviour. When supplies are heavy and prices are low, demand tends to pick up and eventually draw down those heavy supplies. That isn’t always a quick process though.

One way to measure the heaviness of supplies is the stocks-to-use ratio. This is calculated by dividing the July 31 ending stocks of a crop by the amount of total usage (exports and domestic consumption). The higher the percentage, the heavier a crop’s supplies are, relatively speaking.

When we look at peas for example, the 5-year average stocks-to-use ratio is 14% and in 2024/25, that moved up to 17%. The big jump in 2025/26 was mainly caused by the much larger crop. Our forecast for 2026/27 includes a drop in pea acreage and a return to average yields but even then, the 2026/27 stocks-to-use ratio only declines to 24%, still on the comfortable side.

For lentils, the stocks-to-use ratio was already signaling heavier supplies in 2024/25, well above the 5-year average but in 2025/26, that spiked to 63%. Next year, even with a forecast of fewer acres and average yields together with solid exports, the stocks-to-use ratio will remain elevated.

The stocks-to-use ratio for chickpeas dropped in 2024/25 but shot higher in 2025/26. And the situation may not improve in 2026/27, even if yields drop back to average and acres slip a bit. Those heavy stocks carried over from 2025/26 will keep next year’s supplies very heavy.

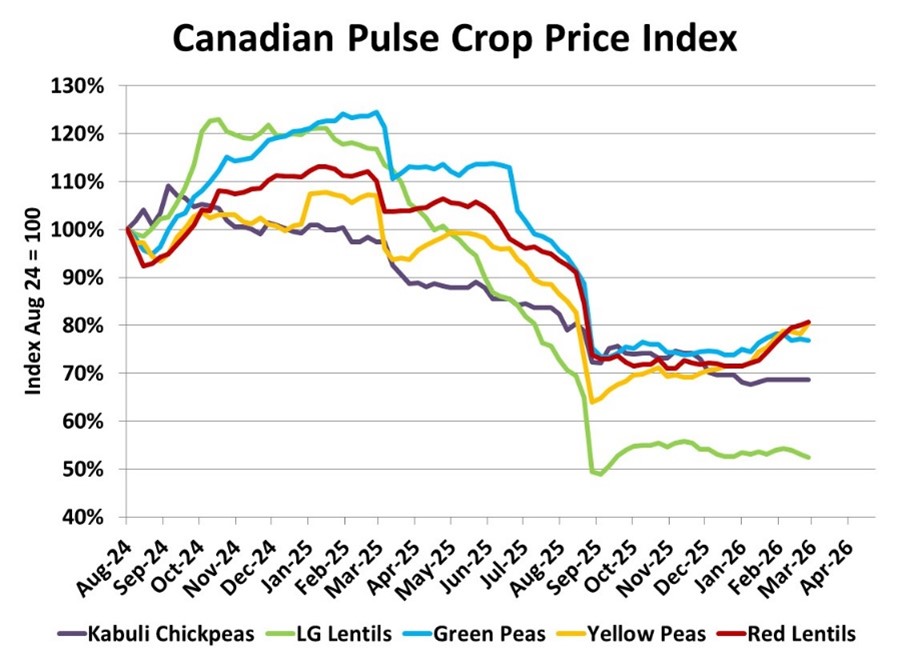
That’s not to say the large supplies won’t allow prices to improve at all. We’ve already seen some gains in pea prices (even before China’s reentry into the market) and red lentil bids are starting to edge higher as well. Rather, the heaviness will limit the potential gains that tend to show up seasonally (for some crops) in spring as well as price potential in 2026/27.

Pulse Market Insight provides market commentary from Chuck Penner of LeftField Commodity Research to help with pulse marketing decisions.
Pulse Market Insight #291

Chinese Pea Demand is Positive but Not the Cure-All

No question, the news that China is dropping its 100% import tariff on Canadian peas is positive for the market. At a time of year when pea exports are normally slowing, renewed shipments to China will keep peas flowing into the system, which will keep prices supported.

Early in 2026, average western Canadian bids for both yellow and green peas are up roughly 60 cents per bushel. We emphasize the word “average”, because some buyers have raised their bids considerably more while others haven’t responded as much. People who were expecting bids to spike following the Chinese tariff announcement are probably underwhelmed with this response, but there are a few reasons for the relatively modest gains.

For one thing, China has been able to access plenty of peas from Russia, which had a record 5.2 mln tonne crop in 2025/26. Even so, Canadian peas are still preferred due to consistency of quality, which should provide a boost in trade. Chinese pea inventories are currently low, which should also add to a solid recovery in Canadian exports.

So far in its 2025/26 Jun-May marketing year, China has imported an average of 175,000 tonnes per month (with Russia as the main origin), which would mean a full-year import program of 2.1 mln tonnes. That said, the drop in pea prices closer to a Chinese corn/soymeal feed value suggests more peas will be imported for the feed channel, in addition to the food and fractionation industry, which could add another 300-400,000 tonnes of imports over the next few months. Under this scenario, Canadian peas would likely supply the food/fractionation demand while Russian peas are imported for the feed market.

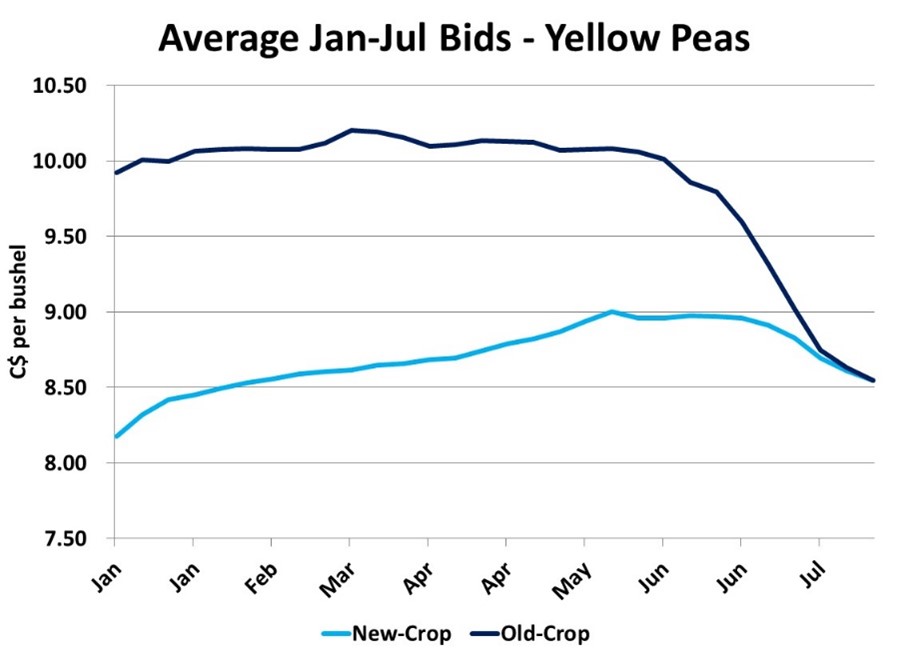
The tariffs aren’t scheduled to drop until March 1, but peas are being assembled ahead of time for export shipments. Even so, the stronger demand pull will be more noticeable in the coming weeks, which should allow bids to firm up a bit more. Keep in mind, stronger prices are typical at this time of year, with seasonal highs for both yellow and green peas in the March-May timeframe.

Unfortunately, Canadian pea exports to China will only be tariff-free for the last five months of the 2025/26 marketing year, not enough time to draw down supplies in a big way. While the increased exports will be helpful, they won’t be able to completely cure the heavy supply situation facing the pea market.

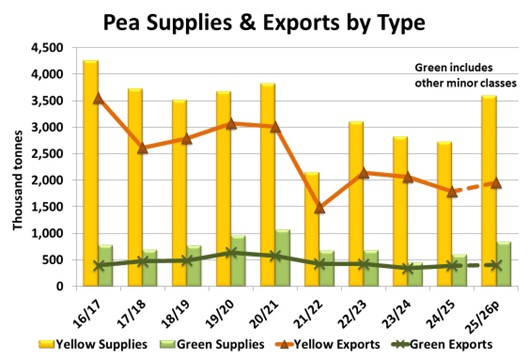
Our estimate of 2025/26 yellow pea supplies is 3.6 mln tonnes and even with increased shipments to China, full-year exports will still end up somewhere around 2.0 mln tonnes. That leaves more than enough yellow peas for feed and seed use, while still boosting ending stocks. It’s a similar picture for green (and minor) peas, with supplies around 850,000 tonnes compared to our export forecast of 400,000 tonnes. That will leave those ending stocks also at multiyear highs.

The bottom line is that while the resumption of pea exports to China is a good thing, it isn’t a quick fix, mainly because of this year’s big increase in Canadian supplies. But there is room for longer-term optimism. If Canadian farmers trim seeded acreage a bit and yields drop back to average, the 2026/27 crop will automatically be smaller. And if China and India don’t increase tariffs in 2026/27 (fingers crossed), a full year of demand from these two major buyers will certainly help draw down supplies and result in a more balanced market.

Pulse Market Insight provides market commentary from Chuck Penner of LeftField Commodity Research to help with pulse marketing decisions.
Joint Letter on the Closure of Federal Agricultural Research Centres

The Honourable Heath MacDonald, P.C., M.P. Minister of Agriculture and Agri-Food

The Honourable Kody Blois, M.P., Parliamentary Secretary to the Prime Minister, House of Commons

February 3, 2026

Re: Closure of Federal Agricultural Research Centres, Including Lacombe, Alberta

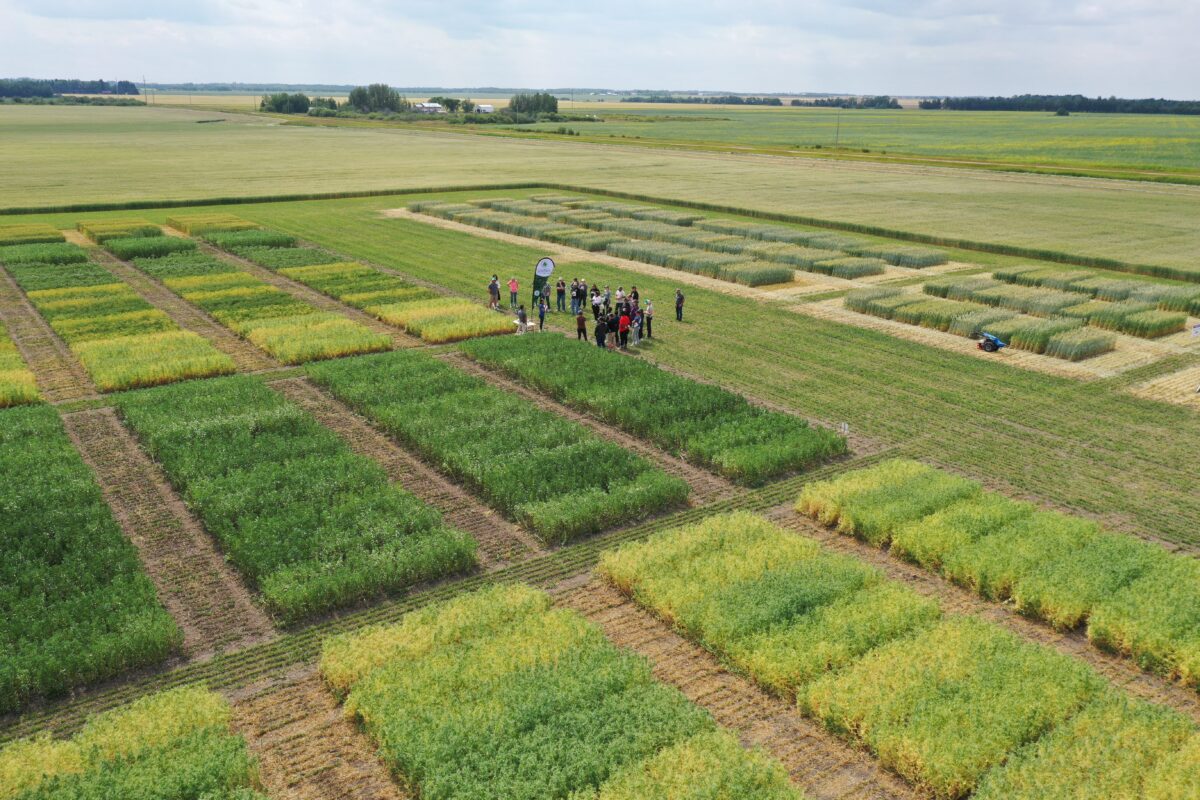
We are writing to express our deep disappointment with Agriculture and Agri-Food Canada’s recent decision to close three federal research and development centres and four satellite research farms across Canada, including the research and development centre in Lacombe, Alberta. Research and development are critical to advancing industries and economies by addressing current challenges and building resilience for the future, and have played a vital role in growing agricultural exports to $100.3 billion in 2024 (AAFC, 2025). In the context of today’s global environment and declining productivity for Canadian agriculture, it is more important than ever to support domestic research capacity to ensure Canada remains a leader in agriculture for years to come.

Public investment in agricultural research has historically delivered some of the highest economic returns of any government expenditure. Independent studies consistently demonstrate that agricultural research and development generate strong multiplier effects by driving productivity growth, improving farm profitability, strengthening rural economies, and supporting downstream processing and export competitiveness. Richard Gray and Stavroula Malla (2007) indicate that the return on investment in agricultural research, for most agricultural sectors, ranges between 30-50%. The steady erosion of government investment in agricultural research over recent decades has already contributed to slower innovation adoption, reduced capacity for long-term applied research, and increased reliance on technologies developed outside Canada. Further reductions risk compounding these challenges at a time when producers are facing unprecedented pressures from climate variability, geopolitical trade disruptions, and rising input costs.

Canada’s agricultural sector operates in a highly competitive global environment. Jurisdictions such as the United States, the European Union, Australia, China and Brazil make robust investments in public-private research partnerships, genetics, climate resilience, and productivity-enhancing technologies. Maintaining and strengthening Canada’s competitive position requires sustained, regionally relevant research capacity.

Equally concerning is the apparent lack of meaningful consultation with stakeholders prior to these decisions. Producer organizations, industry partners, and academic institutions have invested significant financial resources, in-kind support, and expertise in collaborative research conducted at AAFC research and development centres. The lack of clarity surrounding staffing changes raises serious concerns for research funders, who must now assess the risks and consequences for recently initiated and ongoing research. The closure of facilities without prior engagement undermines trust and jeopardizes ongoing research investments and outcomes.

Given the scale and long-term implications of these decisions, there is a clear need for collaborative discussions on the future structure of agricultural research in Canada and the appropriate role of government moving forward. Early and meaningful engagement with industry stakeholders on options for the future use of Federal agriculture research assets is both warranted and welcomed. A transition is required for much of the on-going research as some projects are in the ground already and require time and resources to uncouple from AAFC land, staff and labs. The current timelines will not allow for these programs to proceed this field season, putting a halt to agricultural innovation indefinitely.

Producers and industry stakeholders are not asking the government to act alone. Rather, we seek a stable, predictable public research framework that enables effective partnerships, leverages private investment, and supports innovation that serves the public interest. A transparent and collaborative dialogue will help ensure that Canada’s agricultural research system remains globally competitive, regionally responsive, and capable of delivering long-term economic, agronomic and environmental benefits.

Thank you for your attention to this important matter. We would welcome the opportunity to participate in further discussions on how we can collectively strengthen Canada’s agricultural research and innovation system.

The organizations signed on to this letter include the Alberta Beef Producers, Alberta Beekeepers Commission, Alberta British Columbia Seed Growers, Alberta Canola, Alberta Grains, Alberta Lamb Producers, Alberta Pulse Growers, Alberta Oat Growers Commission, Alberta Pork, Potato Growers of Alberta and the Alberta Sugar Beet Growers. Together, we represent the majority of the over 40000 farmers and ranchers across the province of Alberta.

Sincerely,

C.C.

The Right Honourable Mark Carney, Prime Minister of Canada, P.C., M.P.

The Honourable Danielle Smith, Premier of Alberta, E.C.A., M.L.A.

The Honourable R.J. Sigurdson, Minister of Agriculture and Irrigation, E.C.A., M.L.A.

References

Agriculture and Agri-Food Canada (AAFC). (2025). Overview of Canada’s agriculture and agri-food sector. October 14, 2025. Accessed: February 2, 2026. https://agriculture.canada.ca/en/sector/overview

Gray, R., Malla, S., Gray, R., & Malla, S. (2007). The Rate of Return to Agricultural Research in Canada. Unknown. https://doi.org/10.22004/AG.ECON.273065

APG Launches New Website with Enhanced Features

Alberta Pulse Growers (APG) unveiled its new website today at albertapulse.com. This enhanced resource makes it easy for Alberta pulse farmers to find useful information about growing and marketing pulses, and for consumers to learn how best to eat more pulses.

The APG website is the heart of all APG communications. It is divided into main sections of About Us, Growing Pulses, Eating Pulses, Marketing Pulses, and News & Events, as well as adding Advocacy as a major component to reflect APG’s increased activity in this area.

“When producers look for information, they need it fast and they need to be able to depend on it to be accurate,” said APG Chair Will Muller. “APG’s new website is a reliable source of information that farmers can access from out in the field, or just about anywhere. The new site also provides an opportunity for consumers to learn more about how peas, beans, lentils, chickpeas and other pulses are sustainably produced by Alberta farmers.”

Common questions are answered in the About Us section to save time and reduce frustration, while other topics are also easily found via dropdown menus. New and enhanced features include an event “add to calendar” button, contact forms, simplified dealer list, and a new Research resource library section. The Eating Pulses section is tailored to be a consumer hub for pulse information and recipes, including online ordering of recipe resources for teachers and health professionals, and an email newsletter.

“We are very proud of the resources available through APG for growers and consumers,” Muller added. “This website makes use of the latest technology to put up-to-date, reliable pulse information at the fingertips of visitors when they need it in keeping with APG’s vision of pulses on every farm, on every plate.”

APG is committed to providing the best information in an attractive and responsive format to promote the benefits of including pulses in a sustainable crop rotation and in a healthy diet through research and marketing initiatives to increase the sustainability and profitability of pulse production in Alberta. The Alberta Pulse Growers Commission represents 5,400 growers of field pea, dry bean, lentil, chickpea, faba bean, lupin and soybean in Alberta.

For more information, please contact:
Rachel Peterson, Communications Manager
Phone: 780-986-9398 ext. 108
rpeterson@albertapulse.com