Contact

Nominations Open for 2026 Pulse Industry Innovator Award

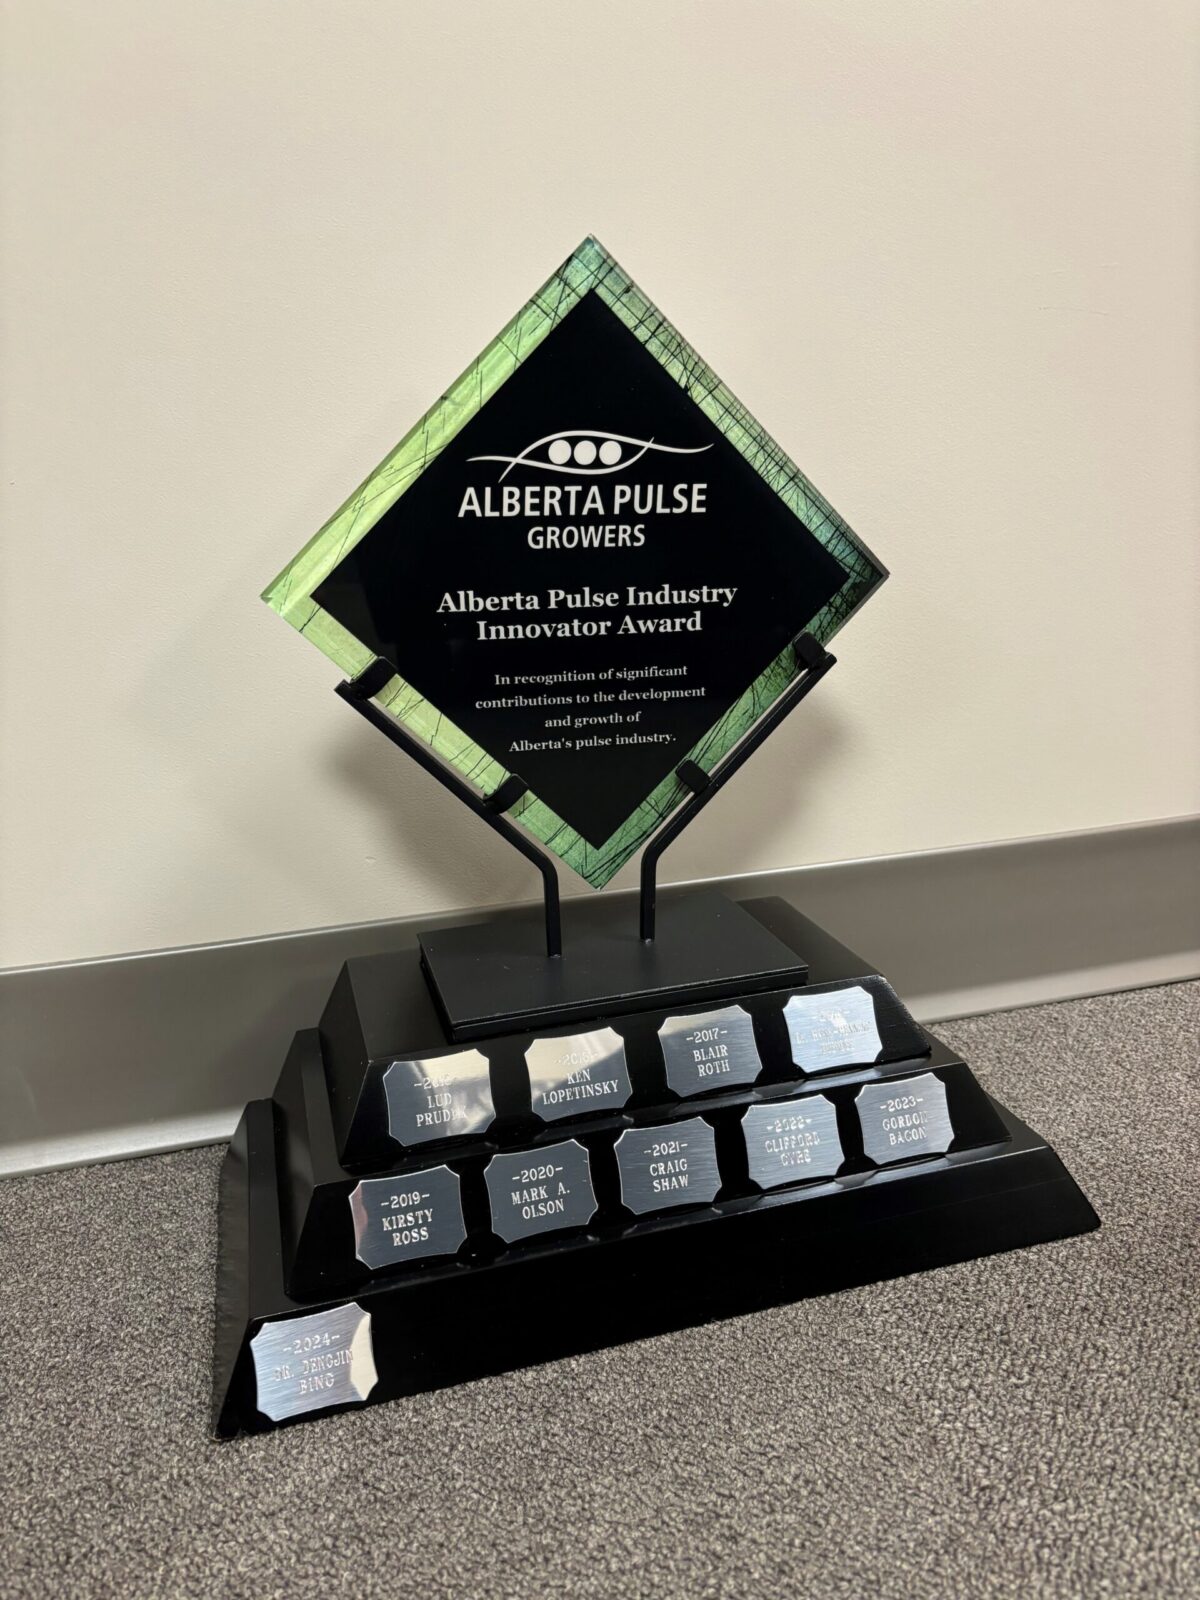
The Alberta Pulse Growers Commission is pleased to announce the 12th annual Alberta Pulse Industry Innovator Award. An industry innovator is a person or organization that has worked to help nurture and shape the pulse industry and has helped contribute to the success of the industry as it is today. Innovators may have contributed to the industry through various areas from production, marketing, research, extension, processing, management, promotion and innovation.

To nominate someone, please complete the Pulse Industry Innovator Nomination Form below.

Nominations may be forwarded to the APG office and will be accepted until December 11, 2025.

2026 APG Pulse Innovator Nomination Form

2026 APG Pulse Innovator Fillable Nomination Form

Pulse Market Insight #271

Serious Damage for the Pea Market

For the last few months, our focus in the pea outlook had mostly been on India and what it might do as the February 28 tariff deadline approached. It turns out this wasn’t the biggest issue for the pea market. Last week, China decided to take out its anger about Canada’s tariffs on Chinese electric vehicles, steel and aluminum on Canadian farmers (again). The 100% tariff on Canadian peas was a complete surprise, as China’s retaliation was expected to come through its investigation into Canadian canola dumping announced last fall.

China has been the dominant buyer of Canadian peas ever since India’s last set of tariffs kicked in back in 2017. When India dropped its pea tariffs in 2023/24 and 2024/25, Canadian exports have been more balanced between these two large destinations. The biggest volumes exported to China have been yellow peas but it is also a large buyer of green and maple peas, which are also included in the 100% tariff.

If past behaviour is any indication, the Chinese tariffs won’t go away anytime soon. This means they’ll likely last into 2025/26 and affect next year’s markets. China has been able to find other sources of peas, when it opened its borders to Russian peas in 2023 and just recently to Ukraine. Whether these Black Sea peas will be able to meet the quality specs for the food and fractionation industry remains to be seen.

Meanwhile, the Indian government has kicked the “tariff can” down the road another three months by moving its deadline for zero tariffs on peas to May 31. On the surface, that seems helpful but won’t likely trigger much new trade for a couple of reasons. First, these short-term deadlines make it difficult for traders to assemble and ship sizable amounts in those time frames. Second and more important, inventories of imported peas are still very large in India, with some reports indicating a million tonnes in storage. Pea prices in India remain under pressure and there’s little interest in bringing in more peas. Canadian exports to India had already dropped considerably in the past 2-3 months and the zero tariff extension won’t reverse that slowdown.

For the rest of 2024/25, Canadian exports of peas will be severely constrained. No more peas will move to China and not many to India. And we still have a simmering trade dispute with the US which has at times been a large buyer of Canadian peas. Some other countries, particularly in South Asia, could buy more peas. In December, for example, Bangladesh was the largest destination for Canadian peas. That said, stirring up more interest in some of these countries could require lower prices. Even so, ending stocks of Canadian peas in 2024/25 will be considerably heavier than expected earlier.

Just as (or maybe more) important is the question about what will happen in 2025/26. There are a few possibilities. One is that India could extend the zero tariffs again until sometime into 2025/26, which could allow a decent fall shipping program and help clear some of the heavy supplies. A resolution with China is also a possibility but feels like a long shot. Again, the Canadian pea market will need increased buying from some countries like Bangladesh that have not been consistent buyers in recent years. Even then, the Canadian pea market feels like it’s setting up for a very difficult year.

Pulse Market Insight provides market commentary from Chuck Penner of LeftField Commodity Research to help with pulse marketing decisions.

Voting Quorum Changed to Ensure APG Meetings Continue to Move Forward with Commission Business

The Alberta Pulse Growers Commission (APG) changed its bylaws to reduce the number of members necessary to conduct an annual or special Commission meeting from 40 to 30 eligible producers.

The Alberta Agricultural Products Marketing Council approved the change on February 24 following a vote by eligible APG members attending the 2025 annual general meeting in January and conversations at all five fall zone meetings.

“We had great turnout at the provincial AGM in January, but sometimes it isn’t easy to get growers out to these meetings,” said APG Chair Shane Strydhorst, who farms at Neerlandia. “If we didn’t have quorum at the AGM, we wouldn’t have been able to hold a vote and would have had to reschedule. We strive for more than our quorum number when we are making decisions because we want everyone to participate.”

Strydhorst added that the board agreed that the move was necessary for several reasons, including the increasing consolidation of farms. The new quorum number brings APG in line with other similar organizations.

Meanwhile, Strydhorst was re-elected as APG Chair following the AGM. He leads an Executive Committee that includes First Vice-Chair Will Muller of Bow Island, and Second Vice-Chair Kevin Auch of Carmangay. APG’s 12-member board also includes Directors Greg Stamp of Enchant, Peter Hoff of Gleichen, Chris Allam of Ardrossan, Peter Konstapel of Spirit River, Beverley Wieben on Fairview, Robert Semeniuk of Smoky Lake, Scott Keller of New Norway, Director-at-Large (Bean) John Kolk of Picture Butte and Director-at-Large (Non-Bean) Michael Bury of Mannville.

The Alberta Pulse Growers Commission represents 5,400 growers of field pea, dry bean, lentil, chickpea, faba bean, lupin and soybean in Alberta.

For more information, please contact:
Rachel Peterson, Communications Manager
Phone: 780-986-9398 ext. 108
rpeterson@albertapulse.com
www.albertapulse.com

Pulse Market Insight #270

Market Signals from Weekly Data

More market transparency, information about how crops are being traded, is always a desirable goal. Timely information about sales and prices helps us do a better job of tracking supply and demand developments and gives us a clearer picture of what’s ahead. Ideally, if farmers and grain merchants would both provide information about the crops they’ve sold and the prices they’ve received, it would fill in a lot of the missing pieces in the market puzzle. But we’re not holding our breath.

Until that happens, we have to work with the information that’s available. While StatsCan is the data source most often mentioned (and criticized), the Canadian Grain Commission provides useful weekly data which offers some clues about market status and strength. This data includes commercial inventories at country elevators and at export terminals, farmer deliveries, shipments from country elevators and exports, among others.

Admittedly, there are some gaps in the CGC data but in our view, the three most important are farmer deliveries, elevator shipments and exports. If we think about the export pipeline, the leading market signal comes from the pace of farmer deliveries, as supplies are pulled into the handling system. Next, the weekly shipments out of country elevators are a strong indicator of how much of a crop is needed at the ports or to be moved south into the US or Mexico. Finally, weekly exports are reported, which shows how much is on its way to other countries. Other bits and pieces of data add more context.

When we look at what these signals mean for peas, the data shows farmer deliveries were above average early in 2024/25, but volumes already started to drop below average in late November. And in the last few weeks, deliveries have been even slower, an advance signal that exports in the weeks ahead will get very quiet. The chart below with pea shipments out of country elevators shows a similar picture and confirms the slowdown.


The slow movement of peas is a clear signal of weaker demand. While that situation could change before the end of 2024/25 (the line for 2023/24 shows what happened when India dropped its tariffs and returned to the yellow pea market), movement of peas generally slows later in the marketing year. And if fewer peas are needed, a meaningful rally becomes less likely. Keep in mind, the CGC data for peas mainly includes yellows, with greens moving mostly by container.

The picture for lentils is more positive. The CGC data mostly includes red lentils as that’s the main type shipped through the elevator system. Weekly farmer deliveries have been close to or above average levels, which signals a strong pull into the elevator system. When it comes to shipments from country elevators to various locations, weekly volumes were slow to start 2024/25 but since the beginning of October, have remained mostly above average, sometimes well above average.


These above-average lentil shipments then turn into strong exports, although export totals can vary considerably from week to week. In general, these signals reveal that global lentil demand is still quite strong and raises the potential for higher prices, especially as on-farm supplies are drawn down.

Of course, the situation in western Canada is only one part of the global market, but it is a large piece of the puzzle for pulse crops. And the value of the information means we continue to advocate for more market transparency in Canada and elsewhere.

Pulse Market Insight provides market commentary from Chuck Penner of LeftField Commodity Research to help with pulse marketing decisions.

Pulse Market Insight #269

Turbulence Ahead for Peas?

The beginning of February marks the start of the second half of the marketing year. The first half of 2024/25 was mostly positive for pulse markets but there could be more turbulent times ahead. Typically, the last half of the marketing year is a lot quieter but this year, trade issues could be throwing several wrenches into the works.

As always, India is front and centre when it comes to pulse outlooks and that’s certainly the case again this year. Import tariffs for yellow peas were set at zero just over a year ago, which allowed a big increase in Indian imports, largely from Canada and Russia. Several deadlines to reinstate tariffs have come and gone, with February 28 as the latest. As supplies of imported peas grew and prices declined, the Indian trade has increased its pressure on the government to reimpose tariffs. Now there’s another signal that the government will return to its previous tariff policy.

Last week, yellow pea prices in India jumped nearly US$50 per tonne after a long series of declines. Possibly not coincidentally, this occurred at the same time as a major convention for Indian pulse traders. This raises the possibility that government officials have tipped their hand about restricting imports with tariffs after February 28.

Canadian exports of yellow peas to India have already been declining in recent months, with only 22,800 tonnes in December, but a shutdown in that trade would be damaging. Through the first five months of 2024/25, Canada has exported 675,000 tonnes of yellow peas to India, 55% of the total. While other countries like Bangladesh have stepped up to buy more in recent months, the absence of India would put a damper on movement of yellow peas.

That said, there are a couple of glimmers of hope for this situation. Indian farmers have responded to the lower prices and cut back on seeded area of peas. The latest reports show 22% fewer acres of peas this year. Satellite vegetation maps show conditions are better-than-average but not as good as last year, suggesting a smaller crop is coming in the next few weeks. Seeded area of chickpeas is also below average, which would mean those supplies will also not be large. One possible outcome is that yellow pea tariffs are reimposed but may not last long. That said, India will need to consume its large inventories of yellow peas and desi chickpeas before prices will rise enough to convince the government to open its doors again.

The trade situation in the US is also volatile but the impact would be less severe. Total Canadian pea exports to the US so far in 2024/25 have only been 42,600 tonnes, half of last year’s pace (the trade data isn’t clear on how many are greens versus yellows). With monthly exports averaging less than 10,000 tonnes, a slowdown or shutdown caused by tariffs wouldn’t be catastrophic. But it’s not nothing either. And for companies and farms that have been filling this demand, it would have a sizable impact.

It’s also not clear that China is in a position to start importing a lot more peas to take up the slack. After very quiet trade for most of 2024, imports did show some strength in October and November but already faded again in December. Plus, Chinese demand is divided between Russian and Canadian peas.

This certainly isn’t a friendly outlook for the pea market, especially yellows. While we’d love to paint a rosy picture, it’s just as important to know the risks ahead as the optimistic possibilities. And as always, events can quickly change and cause other, hopefully more positive, outcomes.

Pulse Market Insight provides market commentary from Chuck Penner of LeftField Commodity Research to help with pulse marketing decisions.
Back to Basics: Field Pea and Faba Meeting

Alberta Pulse Growers’ Zone 3 and Zone 5 present Back to Basics on Feb. 20, 2025 in Fort Saskatchewan, AB. This event features: Mark A. Olson discussing Pea and Faba Agronomy; a Market Update from Suzanne LeClerk of Market Master: Dr. Jenn Walker talking about Mitigating your Risks: Root Rot Complex; APG’s Nevin Rosaasen talking policy: and area farmers discussing their experiences. Register here.

Pulse Market Insight #268

India Situation Update

This is the time of year that we look more closely at the situation with Indian pulse crops, as the rabi season is when Indian farmers plant chickpeas, lentils and peas, the crops we’re more concerned about in Canada. Normally, the focus is on acreage and crop prospects. While those are still important, the added layer of government policy has become a key feature in the outlook. But let’s start with crop production.

This year, Indian farmers started the planting season on a strong note, with pulse acreage running ahead of average. There are some questions about the Indian reports, but they show very small gains later in the season, with total pulse acreage currently 11% less than last year and 12% below the 5-year average. According to these reports, Indian farmers have planted 24.4 mln acres of chickpeas (6% less than last year), 4.3 mln acres of lentils (down 11%) and 2.2 mln acres of peas (12% less).

Of course, acreage is only one part of the production equation. Across much of India, satellite vegetation maps show crop conditions are better than average, with the early harvest scheduled to begin in a few weeks. Keep in mind, conditions were very positive last year; comparing the vegetation maps against last year shows key growing areas in north-central India this year in worse shape. These two comparisons suggest 2025 yield potential could be better than average but less than the 2024 harvest.

This brings us to the other main topic in the outlook, Indian government policy. With acreage and crop prospects smaller than last year, it’s possible the Indian government will decide to keep import tariffs off for peas, lentils and chickpeas. This would help keep food prices low for Indian consumers but wouldn’t make farmers very happy.

The current situation is that import tariffs are set at zero for peas, lentils and chickpeas. The deadline for peas has been extended several times and the latest deadline is February 28, unless it’s extended again. For lentils and chickpeas, the deadlines are March 31 and those can also be extended.

Because the government’s goal for the zero tariffs has been to keep food costs down, prices for the various pulses can be a clue about possible changes in policy. For peas, prices have been dropping ever since the tariffs were zeroed out in late 2023 and have continued to decline steadily as imports from Canada, Russia and elsewhere flowed into India. With Indian pea prices now at the lowest point in years and the harvest soon to arrive, it may encourage the government to impose import tariffs again to protect its farmers.

Desi chickpea prices rose sharply last year in response to a smaller 2024 Indian harvest but have now given back all of those gains. The latest steep declines are showing up as the big Australian crop is now arriving in India and boosting supplies in the country. This could allow the government to reimpose tariffs on desi chickpeas at the end of March. And as yellow peas are a substitute for desi chickpeas, the lower chickpea prices could also support the return of tariffs on peas after February 28.

The situation for lentil tariffs seems a bit clearer. Prices in India are holding steady, in line with the government’s Minimum Support Price and are also helped by the drop in Australia’s recent harvest. The steady prices suggest there’s less chance of tariffs being reimposed on lentils at the end of March.

Crop markets are full of uncertainty and the situation in India is no exception. We are used to the ups and downs in prices that are caused by smaller or larger crops. With the Indian crop getting closer to harvest, that uncertainty is starting to fade. But the unpredictability of government policy remains just as large as ever.

Pulse Market Insight provides market commentary from Chuck Penner of LeftField Commodity Research to help with pulse marketing decisions.

Qualified Alberta Pulse Growers Eligible for 17.5% Tax Credit for Investing in Research

The Alberta Pulse Growers Commission has confirmed that 17.5% of eligible producers’ 2024 check-off payment is eligible for the Scientific Research & Experimental Development (SR&ED) tax credit for their investment in APG-funded research and development projects.

Producers who have paid check-off this past year and have not asked for refunds are eligible claimants for this year’s credits.

For more detailed information about the SR&ED Tax Credit, APG advises you to contact an accountant or the Canada Revenue Agency. For a history of SR&ED with Alberta Pulse Growers visit https://albertapulse.com/growing-pulses/sred-tax-credit/ . A summary of APG research investments in 2023-24 is available at https://albertapulse.com/growing-pulses/research/ .

The federal SR&ED tax program is administered by the Canada Revenue Agency (CRA) and encourages businesses to invest in and perform research and development in Canada.

The SR&ED Tax Credit application forms for individual producers and Canadian controlled private corporations can be downloaded directly from the CRA website at https://www.canada.ca/en/revenue-agency/services/scientific-research-experimental-development-tax-incentive-program.html .

The Alberta Pulse Growers Commission represents 5,400 growers of field pea, dry bean, lentil, chickpea, faba bean and soybean in Alberta. Our vision is to have pulses on every farm, on every plate.

For more information, please contact:
Rachel Peterson, Communications Manager
Phone: 780-986-9398 ext. 108
rpeterson@albertapulse.com
www.albertapulse.com

Winter 2025 Pulse Crop News – APG 35th Anniversary

Welcome to the Winter 2025 special edition of Pulse Crop News in celebration of APG’s 35th anniversary as a commission. Click here to view the entire publication. Click the links below to view individual stories.

If you are an APG member, enter to win a Yeti cooler by sending us your email address here to receive news electronically.

Letter from Minister Sigurdson

Chair’s Report

Development of the Field Pea Industry

APG Commission Milestones

Evolution of Advocacy

Pulse Research

Pulse Canada Congratulations

Grain Growers of Canada Congratulations

Prices – 35 Years of Changes

Nukrop News – Historical President’s Report

Innovator Award Recipients

35 Years of PCN Covers

Past APG Directors Reflect on 35 Years

Alberta Pulse Marketing over 35 Years

Collaboration with AFSC

Celebrating 35 Years of Pulse Recipes

Recipe – Lemony Chickpea Cupcake

Executive Director’s Message